Some time ago we handled a business transfer that, on paper, was an easy one. Good venue, good price, a keen buyer and a seller in a hurry to close. Sometimes, the hurry is the first clue.
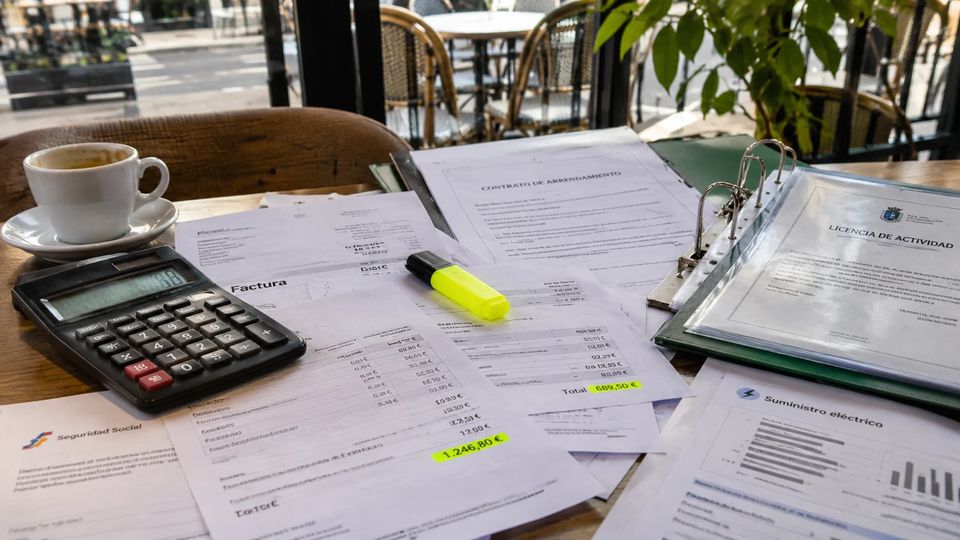
Before signing any document we asked for the usual paperwork to check the business's administrative and financial position. That's when we found that the licence holder had built up several debts: tax liabilities with the Tax Agency, three years of unpaid terrace fees, outstanding waste collection charges and three months' rent owed to the landlord.
The parties agreed to hold back part of the transfer price to be used exclusively to settle those debts before completing the deal. On the agreed day we met and the payments were made on the spot, in front of everyone. We checked each payment as it was made and reviewed the receipts before going ahead with signing the transfer contract.
As a result, the seller settled their obligations, the debts with the authorities were paid and the landlord received the outstanding rent. The new owner took over a business with no known outstanding debts and no later surprises.
I'm telling this story because it's not an isolated case, and because it explains why we ask for the paperwork before anyone pays anything.
Why the previous owner's debts can reach you
When you buy a going concern, you don't just get the premises and the customers. In some cases the law allows debts left by the previous owner to be claimed from the new one:
- The Tax Agency can claim the tax debts of a business activity from whoever continues it.
- Social Security and employees can also pursue whoever takes over the business when there is a business succession.
- The landlord can claim any rent or charges owed, and that can affect the lease the buyer wants to keep or the negotiation of a new one.
There are ways to protect yourself, such as requesting the right certificates before signing. But you have to request them, request the right ones and do it in time.
What we always request
Before a buyer pays a deposit, we request:
- The specific Tax Agency certificate on the debts of the activity being transferred, provided for in article 175.2 of the General Tax Act. It isn't the ordinary certificate of being up to date with payments: it's the one that limits what the Tax Agency can claim from whoever continues the activity.
- Certificate of being up to date with Social Security and the list of employees, if any, with their contracts.
- The lease for the premises and the landlord's confirmation that no rent is outstanding and that they accept the transfer.
- Utility bills: electricity, water and gas, with the latest payments.
- The licences for the activity and the terrace, and whether there are open proceedings or penalties.
- Rental or finance agreements for equipment staying in the premises. Sometimes the coffee machine or the cold room doesn't belong to the seller.
It isn't mistrust. It's what lets you set the price with everything on the table.
When something comes up, you don't always have to walk away
A debt appearing doesn't mean the deal has to fall through. It's often resolved: the seller pays it before signing, it's deducted from the price or part of the payment is held back until it's shown to be settled. What you can't do is sign without knowing.
If you're about to close a business transfer and haven't seen these papers, ask for them before paying anything. And if you'd like us to review them with you, get in touch.
General information, up to date as of the publication date. Every transaction has its own particularities: before making a decision, ask about your specific case.
Image: illustrative recreation, created or edited with artificial intelligence tools.
Meet the team